Client Readiness for AI-Assisted Advisory: A Practical Assessment for CPA Firms
Recent accounting guidance in 2025 and 2026 points in a consistent direction: AI readiness is not mainly a software selection exercise. It is a structured assessment of data, workflows, governance, and responsible use conditions. Most of that guidance is written for firms adopting AI internally, not for CPA firms screening clients for advisory work. Still, the overlap is useful. A defensible client-readiness thesis follows from the available evidence: productive AI-assisted advisory depends less on enthusiasm for AI and more on whether the client can provide usable data, clear ownership, defined processes, and documented guardrails.
Key Findings
- Recent profession guidance frames readiness as a structured assessment across data, systems, governance, workflows, and ethics.
- Data quality and accessibility appear repeatedly as prerequisites for responsible AI use.
- Cross-functional input and named ownership matter, even though direct client-side evidence remains limited.
- A specific, repeatable workflow is better supported than a broad goal to apply AI everywhere.
- Documentation about data handling, privacy, retention, and client communication affects whether work can be handled responsibly.
- The current evidence supports cautious screening questions, not a detailed client scoring model or guaranteed outcomes.
What the current evidence does support about readiness
CPA.com’s 2025 AI in Accounting Report describes readiness as a structured, intentional assessment. Its roadmap highlights data quality, systems interoperability, talent, governance, workflow review, and ethical or regulatory considerations. It also recommends interviews with practice leaders, IT, and operations, which signals that readiness is not confined to one department or one tool decision. The emphasis is on evaluating current conditions before scaling AI use.
The CPA Journal’s 2026 audit-planning guidance points to a similar set of prerequisites. It says firms should evaluate data availability, IT infrastructure, staff competencies, governance policies, and ethical safeguards related to privacy and algorithm transparency. It also stresses that existing processes and controls must be able to support responsible AI use. In that article, pilot selection and success metrics matter because AI should be introduced where value is clear and risk is manageable.
Those sources are mostly firm-side. They do not provide a client-readiness framework for advisory engagements, and the research packet is explicit about that limitation. Still, the evidence supports a narrow interpretation for CPA firms scoping AI-powered advisory services: if the client cannot supply usable data, identify who owns the workflow, describe the target process, or document how information will be handled, the engagement is not ready for responsible analysis.
How We Know
This article relies mainly on profession-adjacent guidance published from 2025 to 2026, with one 2023 oversight source used for policy and client-communication points. The method here is adaptation, not direct proof. The evidence shows what accounting guidance treats as readiness factors. It does not prove a validated client-screening rubric, sector-specific thresholds, or outcome rates for advisory engagements.
Source Notes
CPA.com readiness roadmap: https://cpa.com/sites/cpa/files/2025-06/2025_AI_in_Accounting_Report.pdf
CPA Journal audit-planning readiness guidance: https://cpajournal.com/2026/08/19/leveraging-artificial-intelligence-in-audit-planning
Key finding 1: Data quality and accessibility are the first gate
Across the approved sources, data readiness is the most consistently supported starting point. CPA.com places data quality and systems interoperability inside its readiness assessment. CBIZ states the point more directly: data quality, accessibility, and infrastructure determine AI compatibility. The CPA Journal adds an important caution. Existing processes and controls must support responsible AI use, and AI evidence may be high-volume without being high-quality. That distinction matters for advisory scoping as much as for audit planning.
For a CPA firm assessing a prospective engagement, the practical implication is narrow but useful. Before discussing outputs, savings ideas, or broader transformation, ask whether the client’s data is available, organized, accessible, and credible enough to analyze. If the source material is fragmented, inconsistently structured, or difficult to retrieve, the evidence suggests the engagement is not yet ready for dependable AI-assisted work.
That does not justify a rigid scoring formula. The research packet specifically warns that support is sparse for detailed client-side rubrics, verification methods, or no-go thresholds. So the safest conclusion is simpler: data readiness is a gate, not a guarantee. Passing that gate means the firm has a basis to explore the work. Failing it means the conversation should stay at the level of preparation.
What Changes on Monday
- Ask for a small representative sample of the client data before proposing analysis.
- Check whether the data can be accessed in a usable format, not just whether it exists.
- Separate volume from reliability. More records do not automatically mean better inputs.
- Keep the readiness conversation focused on evidence, not on AI ambition.
Source Notes
https://cpa.com/sites/cpa/files/2025-06/2025_AI_in_Accounting_Report.pdf
https://cbiz.com/services/technology/artificial-intelligence/ai-readiness-assessment
https://cpajournal.com/2026/08/19/leveraging-artificial-intelligence-in-audit-planning
Founder perspective:
“A practical mechanism is to treat data usability as a gate: sample the records, test access paths, and separate volume from reliability. The second-order effect is better pilot selection, because structured inputs narrow risk before advisory judgment begins.”
— James Scott, Founder, Embassy-Row-Project
Key finding 2: Ownership and stakeholder alignment matter, even if direct client-side evidence is limited
The evidence for stakeholder alignment is real, but it is less direct than the evidence for data quality. CPA.com recommends interviews with practice leaders, IT, and operations during readiness assessment. CPA 360 similarly advises firms to confirm an executive sponsor and an operating owner, interview the roles closest to the work, and gather representative evidence. Those recommendations are aimed at accounting firms, not clients. Even so, they support one cautious takeaway for client screening: readiness is weak when no one clearly owns the workflow, systems access, or decision process.
That matters because AI-assisted advisory usually depends on more than one person saying yes. Someone has to explain the current process, someone has to provide or authorize access to the underlying information, and someone has to judge whether the resulting analysis is relevant to the business question. The sources do not give a client-side stakeholder matrix, and they do not support red-yellow-green formulas. They do support asking whether ownership is visible enough to move responsibly.
Strongest objection
Strict ownership screening could exclude clients who are interested in advisory work but have not formalized responsibilities.
Reply
The current guidance favors structured readiness over premature expansion. If ownership is unclear at the start, the safer interpretation is not that the opportunity is bad. It is that the engagement may need a preparatory phase before analysis begins.
This is also where the limits of the evidence should stay visible. The approved research does not establish how much alignment is enough across management, finance, IT, and operations. It supports a modest rule: if the firm cannot identify who owns the process and who can authorize the data, readiness remains uncertain.
Source Notes
https://cpa.com/sites/cpa/files/2025-06/2025_AI_in_Accounting_Report.pdf
https://cpa360leadership.com/ai-readiness-assessment-for-accounting-firms
Founder perspective:
“Operator rule: do not start with ‘Where can we use AI?’ Start with one repeatable workflow, one decision context, and one accountable owner. That tradeoff feels slower, but it preserves review quality and keeps permissions, controls, and outputs legible.”
— James Scott, Founder, Embassy-Row-Project
Key finding 3: Process clarity is more useful than broad AI ambition
The strongest process-related signal in the sources is specificity. CPA.com advises firms to audit current workflows and identify high-friction, repetitive, rules-based processes. The CPA Journal recommends pilot engagements where AI can deliver clear value with manageable risk, especially where data is well structured and teams are experienced. Layer 3 Labs adds a practical advisory angle: AI can help turn reviewed financial data into clearer explanations, scenario models, and client-ready talking points, while the accountant retains review and judgment.
Taken together, that evidence supports a practical screening distinction. A client is more ready when the target workflow is specific and repeatable than when the request is simply to “use AI” across the business. Process clarity gives the firm something concrete to assess: what data feeds the work, what output is expected, and where professional review remains necessary. Broad ambition does not provide that structure.
This section also benefits from restraint. The research packet does not support a full maturity model for client processes, nor does it provide detailed implementation examples for advisory engagements. What it does support is a narrower mechanism: AI-assisted work is easier to scope responsibly when the process is defined enough to review, test, and explain.
For CPA firms, that means the early conversation should stay close to one workflow and one decision context. In some cases, that may fit a performance-based discussion later. But the evidence here supports readiness screening, not pricing claims or outcome promises.
Source Notes
https://cpa.com/sites/cpa/files/2025-06/2025_AI_in_Accounting_Report.pdf
https://cpajournal.com/2026/08/19/leveraging-artificial-intelligence-in-audit-planning
https://layer3labs.io/guides/ai-for-cpas
Founder perspective:
“The contrarian point for CPA firms is that AI enthusiasm is often the least important signal. If data access, workflow ownership, and privacy rules are unclear, the hidden cost is scope drift before any analysis creates value.”
— James Scott, Founder, Embassy-Row-Project
Key finding 4: Documentation and policy readiness affect whether the engagement can be handled responsibly
The documentation question is not whether every client has a perfect policy stack. The supported question is whether the parties can document how AI will be used and how client information will be handled. The Tax Adviser emphasizes firm policies, process management, client communication, data protection, and informed consent where necessary. CPA.com’s AI due diligence material highlights questions about data privacy, model accuracy, security, governance, and an evidence checklist for responsible adoption. Layer 3 Labs adds practical points such as data-processing agreements, checking whether vendors use client data for model training, retention policies, staff rules on what may be entered, and engagement-letter disclosure of AI tool usage.
For client-readiness screening, the implication is straightforward. A promising advisory idea is not enough if the parties cannot explain the handling of client data or communicate AI use clearly. Documentation readiness can be modest and still meaningful. The evidence supports clarity about data handling, privacy expectations, retention, and client communication. It does not support inventing a long artifact checklist for advisory work.
That distinction matters because governance can otherwise become vague. The approved sources repeatedly tie responsible AI use to documented controls and communication, not just to technical capability. So a CPA firm can reasonably treat documentation and policy readiness as part of the go or pause decision.
Source Notes
https://thetaxadviser.com/issues/2023/dec/ai-and-the-importance-of-firm-oversight
https://cpa.com/ai
https://layer3labs.io/guides/ai-for-cpas
Conclusion
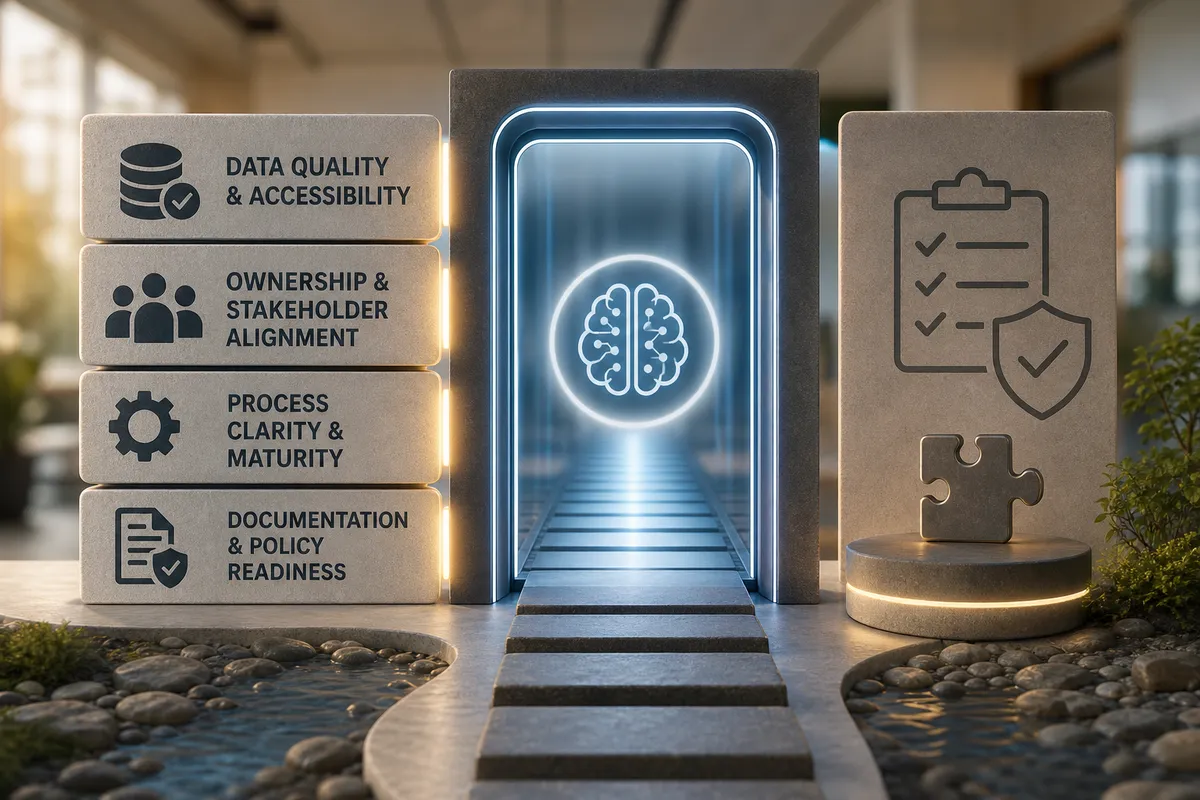
The available evidence supports one practical thesis for CPA firms: client readiness for AI-assisted advisory is best treated as a pre-engagement screening exercise, not as a sales conversation about AI in the abstract. Four questions are well supported by current guidance. Is the data usable? Is there clear ownership? Is the target process specific and repeatable? Can the parties document governance and client communication?
That approach may feel slower than broad expansion, but the profession guidance in the approved sources consistently favors structured readiness, pilot discipline, and responsible data handling. The limits are clear too. The evidence is stronger on firm-side readiness than on client-side scoring. That is why the safest operational move is a cautious screen, not an elaborate framework.
If the firm wants a structured next step, invite readers to use Tax Lens AI’s free assessment or ROI assessment to evaluate whether an advisory opportunity has the basic data, process, and governance conditions for analysis.