How CPA Firms Can Set Evidence Standards for AI-Generated Advisory Recommendations
The dated finding is narrow but useful: the CPA.com 2025 AI in Accounting Report says AI accounting workflows are incorporating human-in-the-loop verification, confidence thresholds, documentation traceability, and audit trails. That matters because AI is entering tax, audit, and advisory services, yet the accepted sources in this research do not support delegating professional responsibility to software. The defensible thesis for accounting firms is this: AI-generated recommendations should remain draft work until source evidence, testing, traceability, confidence-based review where applicable, and named human approval support the client-facing conclusion.
Key Findings
- AI can assist drafting, but the cited accounting sources keep professional judgment with the practitioner.
- CPA.com’s 2025 report supports human-in-the-loop verification, confidence thresholds, traceability, and audit trails.
- SkillAbility states that AI-generated analysis is not audit evidence merely because it appears in a workpaper.
- Rightworks says AI-generated tax advice, memos, or client communications should be reviewed by a licensed professional before reaching a client.
- CalCPA’s audit discussion supports evaluating source-data reliability and understanding whether a tool uses deterministic or probabilistic methods.
- The sources support governance and review more directly than detailed client-signoff protocols or exact calculation-threshold designs.
The defensible standard: AI can draft, but evidence has to carry the recommendation
Evidence-gated AI begins with a simple distinction: an AI system may draft an idea, summary, or analysis, but the recommendation has to rest on evidence a professional can inspect. CPA.com’s 2025 report describes AI accounting systems that use confidence thresholds, human-in-the-loop verification, documentation traceability, and audit trails. That is not the same as saying every AI output is reliable. It supports a narrower operating standard: the firm should be able to connect a conclusion back to reviewed materials and a human approval decision.
Rightworks summarizes accounting-firm AI policy expectations in similar terms. Practitioners remain responsible for AI-assisted work, and outputs should be reviewed and verified before use in filings or advice. SkillAbility adds an important boundary for audit workpapers: AI-generated analysis does not become audit evidence simply because it appears in the file. The engagement team still has to decide what evidence is appropriate under the applicable standards.
How We Know
This article uses the supplied source packet, mainly CPA.com’s 2025 report excerpt and accounting-firm governance articles from Rightworks, SkillAbility, CPA 360, CalCPA, and cpai.com. The evidence window is limited to those excerpts. It supports verification, documentation, review, traceability, audit trails, and caution about overreliance. It does not prove a profession-wide standard for AI-generated savings recommendations.
Source Notes
Relevant sources include https://cpa.com/sites/cpa/files/2025-06/2025_AI_in_Accounting_Report.pdf, https://rightworks.com/blog/ai-policy-template-accounting-firms, and https://getskillability.com/ai-governance-accounting-firms. These sources support the article’s governance thesis, not a claim that one evidence model is mandatory for every firm.
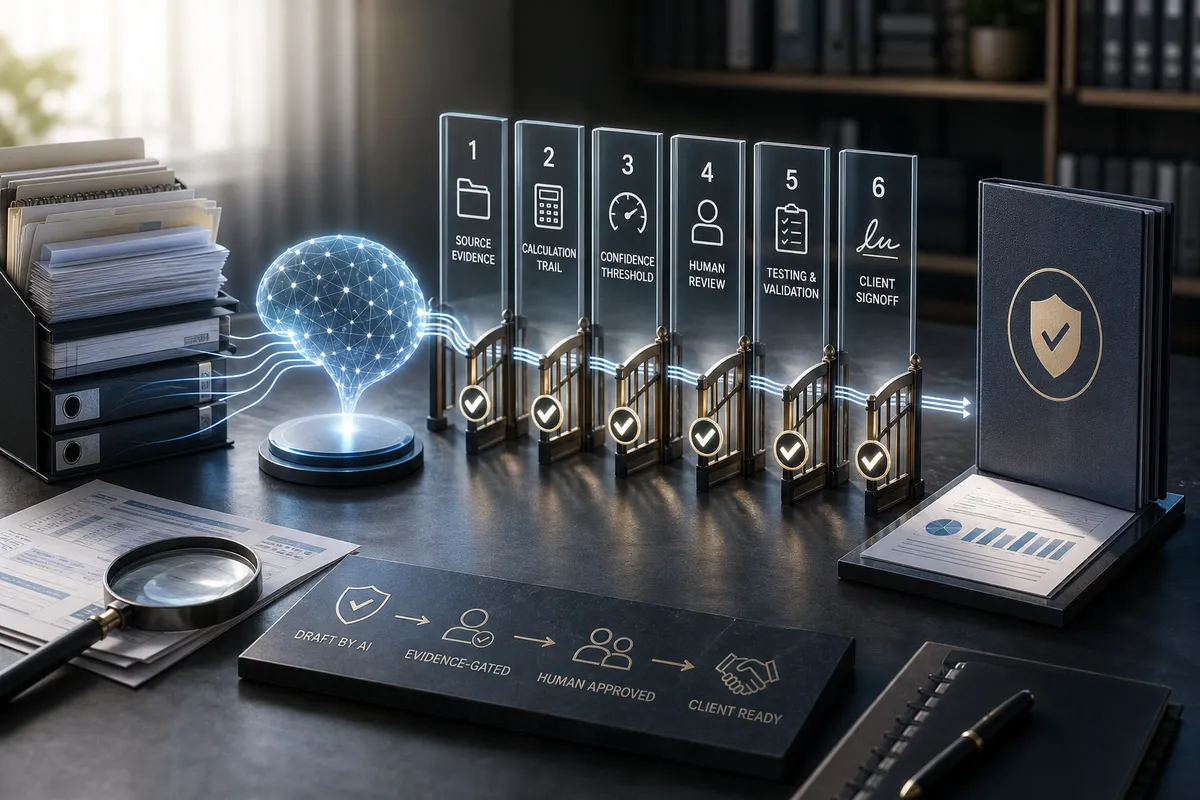
Six evidence gates before an AI-assisted advisory recommendation reaches a client
The practical control is a short gate sequence that prevents AI output from moving straight into client communication. Because the cited materials include audit, tax, and AI-policy sources rather than a profession-wide advisory-savings standard, the six gates below are an interpretation of the cited governance sources, not a formal standard issued by those sources.
| Gate | What the firm checks | Evidence basis |
|---|---|---|
| Approved use case and tool | The work fits permitted uses, approved tools, and data boundaries. | CPA 360 and Rightworks discuss approved tools, permitted uses, and secure client-data handling. |
| Source evidence obtained | The file identifies the records, documents, or other evidence used. | SkillAbility calls for obtaining source evidence and validating output. |
| Output tested | The recommendation is checked against reliable sources, established methods, or firm review procedures. | Rightworks calls for documenting how outputs were tested; Firm of the Future recommends quality-control checks. |
| Traceability retained | The conclusion links back to supporting evidence. | CPA.com identifies documentation traceability and audit trails in AI workflows. |
| Human reviewer named | A person owns final approval, with review matched to risk. | SkillAbility calls for named human final approval; CPA.com emphasizes human-in-the-loop verification. |
| Client communication approved | The client-facing wording is reviewed before delivery. | Rightworks says AI-generated tax advice, memos, or client communications should be reviewed by a licensed professional before reaching a client. |
For AI-powered tax and advisory services, the gates should be treated as a minimum screening discipline. They do not prove that a savings idea is correct. They make clear what has been checked before the firm treats the draft as professional work product.
What source-document requirements should cover
Source-document requirements should start with identification, not a broad claim about certainty. A recommendation file should say what client materials were used, such as the documents, records, contracts, or expense data the firm was authorized to review. The available sources do not provide a detailed evidence hierarchy for advisory savings work, so the policy should avoid pretending that such a hierarchy has been established by the cited materials.
The next requirement is separation. AI-generated summaries should be labeled as summaries, not as the underlying evidence. SkillAbility’s audit-policy principle is the useful guardrail: AI-generated analysis does not become audit evidence merely because it appears in a workpaper. Applied cautiously to advisory work, that means the firm should keep the reviewed source material distinct from the AI’s narrative or suggested conclusion.
Reviewers should also consider source-data reliability and methodology. CalCPA’s audit article warns that practitioners cannot treat AI as an unvetted black box and should understand whether a tool relies on deterministic logic, meaning exact mathematical calculations, or probabilistic models, meaning predictive patterns and generative assumptions. That distinction matters when a recommendation depends on calculations or assumptions.
A confidentiality and data-boundary check belongs before client materials enter an AI workflow. Rightworks and CPA 360 discuss approved tools, secure handling of client data, data classification, and permitted uses. The supported requirement is limited but important: do not put client information into an AI process unless the firm’s policy permits the use, tool, and data handling.
Finally, tax and advisory conclusions need professional review. cpai.com warns that generative AI may misinterpret standards, laws, regulations, context, or nuance.
How to treat calculation trails and confidence thresholds without overclaiming
Confidence thresholds should be treated as review triggers, not automatic approvals. CPA.com’s 2025 report says systems increasingly flag transactions based on confidence thresholds, inviting accountants to act as reviewers. The supplied research does not prescribe exact percentage thresholds, escalation bands, or approval cutoffs for advisory savings recommendations.. A firm can adopt thresholds internally, but the article’s evidence supports the narrower claim that confidence information can help route human review.
Calculation trails require the same restraint. The accepted sources support documenting why AI was used, how outputs were tested, and how conclusions link back to supporting evidence. They do not supply a detailed protocol for retaining every input, formula, intermediate step, version history, recalculation, or reviewer signoff in an advisory savings file. Where a recommendation depends on calculations, the safest source-grounded requirement is reconstructability for professional review: the reviewer should be able to understand what evidence was used, what method was applied, and why the conclusion follows.
Strongest Objection
A firm leader may object that this standard slows advisory delivery and reduces the value of AI, especially if the AI is only proposing a first-pass savings idea.
Reply
The sources support review because AI outputs can be wrong, incomplete, or context-poor. Firm of the Future describes generative AI as non-deterministic and recommends quality-control checks. cpai.com warns against indiscriminate reliance without critical analysis. The point is not to turn every draft into an audit engagement. It is to prevent an unverified AI suggestion from being presented as a validated client recommendation.
If the firm cannot reconstruct the evidentiary basis well enough for professional review, the recommendation should not be presented as validated.
Founder perspective:
“The risky assumption is that AI speed automatically expands advisory capacity. In CPA firms, unsupported savings ideas create review debt: every undocumented source, threshold, and calculation becomes partner time before it becomes client value.”
— James Scott, Founder, Embassy-Row-Project
Human review has to be assigned, documented, and risk-aware
Human review is the mechanism that turns AI output into accountable professional work. SkillAbility supports naming the human who owns final approval, validating output, exercising professional judgment, and reviewing at the required risk level. Rightworks is direct: human professional judgment and review cannot be outsourced to AI, and AI-generated tax advice, memos, or client communications should be reviewed by a licensed professional before reaching a client.
That review should be more than a formatting pass. The reviewer should know what the AI was asked to do, what source materials were used, how the output was tested, and where uncertainty remains. CPA 360 recommends making human review explicit in a project charter by stating who decides, who contributes evidence, what tradeoff is acceptable, and when the decision will be reviewed. That supports an accountability record without requiring the article to invent a detailed workflow.
cpai.com provides the risk rationale. Generative AI may lack context and nuance, and reliance without critical analysis may lead to errors or omissions. CalCPA’s black-box warning points in the same direction: a reviewer should understand enough about the method to judge reliability.
What Changes on Monday
- Define permitted AI use cases for advisory drafting and client communications.
- Require files to identify source materials before an AI-assisted recommendation advances.
- Label AI summaries separately from source evidence.
- Record how the output was tested or why it was not used.
- Name the professional who approves the client-facing recommendation.
- Treat confidence flags as prompts for review, not as proof.
These steps fit Accounting Firms that want AI assistance without treating software output as professional judgment.
Conclusion
An AI-assisted advisory recommendation should become client-ready only after the firm can show source evidence, traceability, output testing, confidence-based review where applicable, named human approval, and approved client communication. That is the defensible standard the supplied sources support. The limitation is equally important: the research supports governance, verification, audit trails, documentation traceability, and human review more strongly than it supports detailed client-signoff rules or exact calculation-threshold designs for savings Recommendations. Firms should build policies within that boundary.