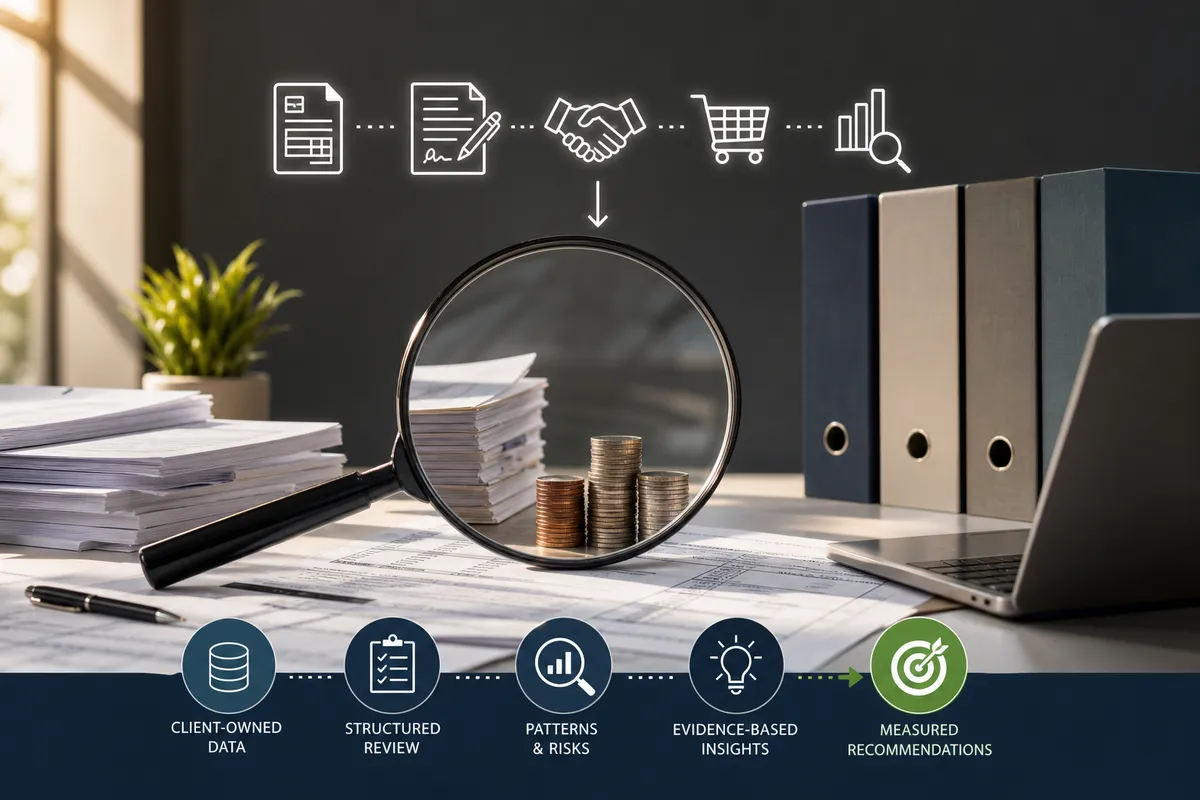
Turning Vendor Spend Reviews Into an Advisory Entry Point
By 2026, the defensible finding is narrow but useful: CPA.com resources place spend and expense management inside Client Advisory Services, while vendor spend analysis sources describe structured reviews of supplier expenses, Contracts, invoices, pricing patterns, and accounts payable data. That combination gives CPAs a practical advisory opening without requiring a broad transformation claim. The newsworthy point is not that every firm can become a procurement consultant. It is that Accounting firms can begin with client-owned evidence, test one vendor-spend category, and turn documented patterns into measured Recommendations.
Key Findings
- Spend and expense management appears in CPA-oriented Client Advisory Services content.
- Vendor spend analysis focuses on supplier-level visibility, not every operating cost.
- Source materials repeatedly name invoices, Contracts, spend data, and AP reports.
- Contract comparison is a recurring test for overcharges and off-contract purchases.
- Expansion into Facilities & Real Estate, insurance, technology, and utilities is supported only as a cautious path.
- Monitoring recovered overpayments, realized Savings, and recurring issues keeps the review evidence based.
The defensible thesis: start advisory with visible vendor spend, not a sprawling transformation project
The thesis is simple: a vendor spend review can be a practical entry point for AI-powered advisory services because it begins with records the client already has. The supported raw materials are Expense data, invoices, supplier records, accounts payable reports, and active Contracts. Ramp defines vendor spend analysis as collecting, cleaning, and reviewing supplier-level spending, including who is being paid, what is being purchased, how often purchases occur, and whether the spend aligns with contracts and business needs. CPA.com’s resource taxonomy places spend and expense management under Client Advisory Services, and one CPA.com webinar title frames spend management as an entry point for scalable advisory.
That evidence supports a focused advisory conversation. It does not prove that every firm should launch a full procurement consulting practice, nor does it establish detailed guidance on pricing, staffing, professional risk, independence, or client communication. The research packet is stronger on what gets reviewed than on how CPAs should package the engagement.
How We Know
The evidence base combines CPA-oriented resource pages, vendor spend analysis explanations, vendor monitoring guidance, and commercial spend-review service descriptions. The useful window is current practice content, including materials dated 2024, 2025, and 2026, plus undated CPA.com resources supplied in the research packet. The method here is claim matching: each article point is limited to concepts directly present in those sources. The evidence does not prove guaranteed Savings, a standard CPA workflow, or a universal path from a first review to larger advisory work.
Founder perspective:
“Operator rule: do not review every vendor with equal intensity. Prioritize by financial impact, recovery potential, implementation effort, and business risk, because exhaustive review can bury the few discrepancies clients can actually act on.”
— James Scott, Founder, Embassy-Row-Project
Five findings the article should make clear
First, spend management is already appearing in CPA-oriented advisory content. CPA.com lists Client Advisory Services alongside spend and expense management resources, which is enough to discuss the topic inside an advisory frame for Accounting firms.
Second, vendor spend analysis is narrower than general spend analysis. The Ramp source distinguishes supplier-level analysis from broader spend analysis by focusing on vendors, supplier terms, consolidation opportunities, and vendor-linked risks. That boundary matters because a first engagement can avoid drifting into every cost category.
Third, the review depends on evidence rather than opinion. Accepted sources repeatedly refer to vendor contracts, invoices, spend data, accounts payable reports, categories, pricing patterns, and usage patterns. Those records give the work a document-based starting point.
Fourth, contract comparison is a core test. Venminder identifies vendor spend that exceeds agreed costs or expected volumes as a red flag and recommends reviewing invoices for unauthorized work and validating scope.
Fifth, broader categories can follow only when the evidence supports it. Blackspire’s service page names Technology & Software, Energy & Utilities, Payment Processing, Facilities & Real Estate, and Insurance & Benefits. Tax Lens AI’s terminology also includes Fleet & Logistics and HR, Payroll & Insurance. Those examples support a cautious expansion path, not a proven cross-sell formula for every CPA firm.
Sixth, monitoring matters. The Salt Group discusses tracking recovered overpayments, realized Savings, vendor performance, and recurring cost issues. That supports measuring outcomes after findings are presented.
Founder perspective:
“The conventional mistake is to sell vendor spend review as procurement transformation. For accounting firms, the cleaner advisory entry point is narrower: reconcile AP reports, invoices, and contract terms in one category first.”
— James Scott, Founder, Embassy-Row-Project
What a vendor spend review actually examines
A vendor spend review is a systematic examination of supplier contracts, pricing, invoices, and spend patterns. The supported issues include pricing drift, contract gaps, overcharges, off-contract purchases, and renegotiation opportunities. In plain terms, the review asks who the client pays, what the client buys, how often the purchases happen, and whether the spending matches contract terms, documented scope, procurement goals, and business needs.
The engagement boundary should stay visible. The sources support a document review and supplier-level analysis. They do not provide enough authoritative CPA-specific detail to assert a standard timeline, staff model, pricing model, independence protocol, or exact deliverable set. That limitation is useful, because it keeps the first project from being oversold.
A compact intake checklist can remain evidence based:
- Vendor master list or supplier list.
- Accounts payable exports by vendor and period.
- Recent invoices for selected vendors or categories.
- Active Contracts and known contract terms.
- Spend categories and supplier descriptions.
- Renewal dates, if documented.
- Notes on authorized scope, service requirements, or change orders when available.
This is where a Line item audit approach can be useful, but only in the narrow sense supported by the sources: comparing invoice-level and supplier-level records against contracts, pricing, usage, and documented scope. It is not a promise that every discrepancy will produce recoverable money.
The mechanism: how invoices and contracts become advisory Recommendations
The mechanism starts with visibility. Vendor spend has to be consolidated and categorized so the client can see spending by supplier, category, product or service, and period. Ramp describes consolidation and categorization as early steps in vendor spend analysis. Without that view, the review is likely to remain a stack of invoices rather than a decision record.
The next move is comparison. Venminder’s guidance supports checking whether spend conflicts with agreed costs, anticipated volumes, authorized work, or the scope and scale of services. The Salt Group adds that negotiations should be prepared with documented pricing differences, usage data, contract terms, service requirements, and benchmarks where available.
A practical review can move through five evidence-based steps:
- Gather invoices, Contracts, AP reports, and category data.
- Categorize supplier spend by vendor, period, and service type.
- Compare invoices with agreed pricing, volume, scope, and documented changes.
- Prioritize issues by financial impact, recovery potential, implementation effort, and business risk.
- Track recovered overpayments, realized Savings, vendor performance, and recurring issues.
What Changes on Monday
For an Accounting firm, the Monday action is not to announce a new practice line. It is to select one vendor-spend category, request the documents above, and define the review question before analysis begins. A narrow question might be whether invoice pricing matches contract terms in one category or whether repeated charges suggest a recurring issue. The output should be Recommendations tied to cited records, not broad claims about transformation.
Founder perspective:
“The mechanism is contract-to-invoice matching: consolidate supplier spend by vendor, period, and service type, then flag pricing drift, unauthorized scope, or volume variances before recommendations become vendor-negotiation evidence.”
— James Scott, Founder, Embassy-Row-Project
Why this can fit CPA advisory conversations
The CPA connection should be stated carefully. CPA.com’s materials place spend and expense management within Client Advisory Services, and the supplied webinar title calls spend management an entry point for scalable advisory. BMSS, a CPA and advisory firm, discusses strategic vendor review in connection with strengthening a 2026 budget and using annual spending data to support vendor negotiations. Together, those sources support the idea that vendor spend can be part of an advisory conversation.
They do not show that CPAs have special authority over procurement decisions, vendor negotiations, or contract interpretation. They also do not establish a standard CPA engagement structure. A fair interpretation is that CPAs already working with client financial records may be positioned to help clients see spend patterns, provided the work stays within a documented scope and does not replace procurement, legal, assurance, tax, or vendor-management expertise.
Strongest Objection
A vendor spend review may sound like procurement consulting under another name. The research packet also contains commercial sources, so claims about Savings and service value should be treated cautiously.
Reply
That objection is valid if the project is sold as a sweeping cost-reduction promise. It is less persuasive when the first project is limited to evidence the client owns: Expense data, invoices, Contracts, supplier categories, and documented pricing differences. The advisory value is the conversion of those records into decision-ready Recommendations.
Source Notes
- CPA.com places spend and expense management in Client Advisory Services resources: https://cpa.com/resources/all
- CPA.com’s webinar title frames spend management as an advisory entry point: https://cpa.com/webinars/spend-management-entry-point-scalable-advisory
- Ramp defines vendor spend analysis at the supplier level: https://ramp.com/blog/vendor-analysis
- Venminder supports contract-versus-invoice monitoring: https://venminder.com/blog/vendor-spend-analysis-monitoring
- BMSS connects annual spending data with vendor review for a 2026 budget: https://bmss.com/strengthening-your-2026-budget-through-strategic-vendor-review
Conclusion
Vendor spend reviews give Accounting firms a cautious way to begin advisory work with client-owned evidence: Expense data, Contracts, invoices, AP reports, and supplier patterns. The supported case is focused, documented, and measured. It is not a guarantee of Savings or proof that every firm can expand into every category. The next step should be narrow enough to test the value before expanding into Facilities & Real Estate, Fleet & Logistics, HR, Payroll & Insurance, or other categories.
Invite Accounting firms to start with a focused ROI Assessment for one vendor-spend category before expanding the conversation into broader Recommendations.